

Credit Sesame: Grow your score
by Credit Sesame, Inc.
4.7
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.7
- Price
- Free
- Download
- 5.00M
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
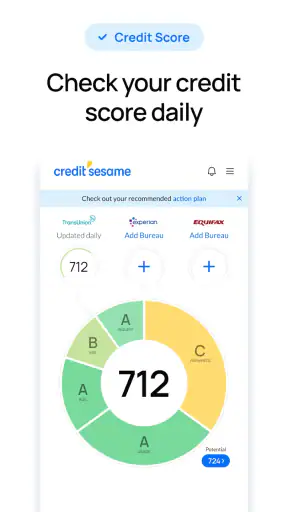
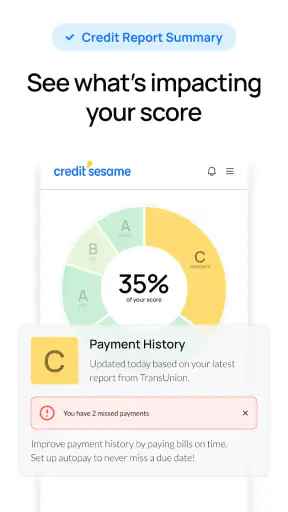
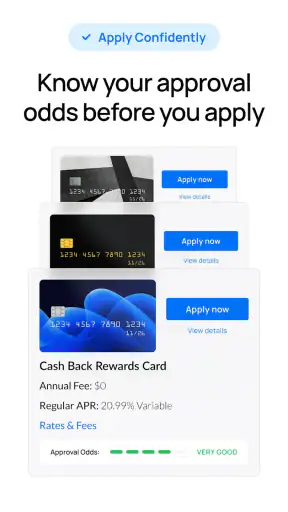
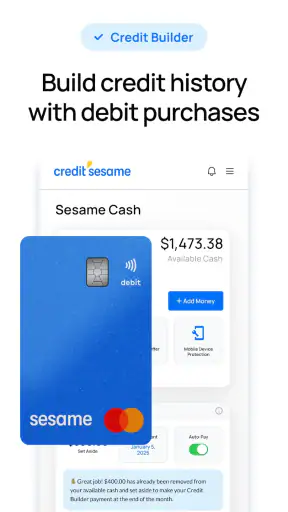
 Analysis by Getfullapps
Managing credit can feel unnecessarily scattered: one app shows a score, another sends account alerts, and your own bank may offer only a narrow view of what is happening. Credit Sesame takes a broader approach as a free finance app from Credit Sesame, Inc., bringing credit monitoring and score-building guidance into one place. I found it most useful as a regular check-in tool rather than a magic button for repairing credit overnight.
The important question is not simply whether the app is popular or free. It is whether its way of presenting credit information matches how you make financial decisions. If you want a straightforward place to watch changes, notice warning signs, and understand the habits that affect your score, it is easy to recommend. If you need detailed budgeting, full debt-management planning, or a complete replacement for official lender documents, you may prefer a different kind of finance service alongside it.
What I looked for before deciding whether it is worth using
My first decision criterion was clarity. Credit information is only useful when I can tell what changed, why it matters, and what action is sensible. A score by itself is not a plan. I paid attention to whether the app encourages calm, repeatable monitoring instead of making every small movement feel like an emergency.
The second criterion was usefulness between major financial events. Many people check credit only when applying for a card, renting a home, or seeking a loan. I think the stronger use of this app is earlier: checking in routinely, noticing unfamiliar activity, and learning which behaviors deserve attention before an application becomes urgent.
I also considered the difference between education and control. An app can help me understand my credit, but it cannot rewrite a lender’s decision or instantly remove accurate negative information. That distinction matters because the most responsible credit tool is one that supports better choices without encouraging unrealistic expectations.
Credit Sesame is available at no cost, which makes trying it low-risk for someone who wants a dedicated credit companion. It is rated for Everyone, so its presentation is intended for a broad audience rather than a specialist financial professional. The app has been available since June 28, 2012, and its current release is version 7.30.1 for devices running operating system version 10 or later.
Its scale also suggests that it has become familiar to many mobile users: the app has passed five million installs, with an average rating of 4.7 from roughly 196 thousand ratings and about 32 thousand written reviews. Those figures do not replace personal judgment, but they do make it easier for me to see the app as an established option rather than an experiment.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
The everyday workflow that makes it useful
My preferred way to use a credit app is not to stare at it every day. I would open Credit Sesame on a regular schedule, review the current picture, and then focus on changes that require action. This reduces the temptation to overreact to normal fluctuations and turns the app into a simple financial habit.
A realistic example is preparing to rent a new apartment. Instead of discovering a problem when a landlord checks credit, I could use the app beforehand to look for unexpected changes or signs that an account needs attention. If something looks unfamiliar, the sensible next step is to investigate through the relevant creditor or official account, not assume that the app itself can settle the dispute.
Another useful scenario is after paying down a balance. I would not expect an immediate score transformation, because credit reporting and scoring do not work like a live progress bar. The better approach is to treat the payment as a positive financial action, then use later check-ins to see whether the overall picture changes over time. That mindset is one of the app’s most important lessons.
The best habit is to use the score as a signal, not as a grade. A lower number does not automatically mean that every financial decision is wrong, and a higher number does not guarantee approval for a particular product. Credit Sesame is more valuable when it helps me ask better questions about timing, balances, applications, and account activity.
Where Credit Sesame wins over simpler alternatives
The app’s clearest advantage is concentration. A bank’s built-in credit feature may be convenient, but it can be limited to that institution’s relationship with me. Credit Sesame is designed specifically around credit awareness, so the experience feels more focused than a general checking-account app that happens to display a score.
It also has an advantage over checking a score only when applying for something. That occasional approach leaves long gaps in awareness. A dedicated app encourages me to make monitoring part of normal money management, which can be especially helpful for people who have previously ignored credit until a problem appeared.
The alerts are another practical strength. Notifications can be useful when they draw attention to a meaningful change instead of requiring me to remember to inspect everything manually. I would still review an alert carefully rather than treating it as proof of fraud or an error. The alert is the prompt to investigate, not the investigation itself.
I also appreciate the app’s educational role. Credit terminology can be intimidating, particularly for someone building a credit history or recovering from past mistakes. Having explanations and guidance in the same environment as the score makes it easier to connect a financial behavior with a possible consequence.
There is a subtle benefit in separating monitoring from borrowing. A lender’s app naturally emphasizes its own products and accounts. Credit Sesame’s main purpose is to help me observe and understand credit, so it can serve as a neutral-feeling starting point for someone who wants to learn before shopping for another financial product.
Where the experience needs a realistic interpretation
Free does not mean frictionless. A finance app may present recommendations or opportunities connected with credit, and I would read those carefully rather than assuming every suggestion is ideal for my situation. A product that appears convenient can still have terms, eligibility requirements, or costs that need separate evaluation. The app can help me discover options, but it should not make the decision for me.
I would also avoid treating one displayed score as the universal answer to “How good is my credit?” Different lenders can use different scoring models and information at different times. That means a score inside the app is useful for monitoring direction and spotting changes, but it may not match the exact number used in a future application.
Another limitation is that awareness does not equal authority. If an account is wrong, I would gather the relevant details and contact the creditor or the appropriate reporting organization. If I am trying to negotiate debt, create a complete household budget, or plan a complicated repayment strategy, I would want tools designed specifically for those tasks rather than expecting a credit-monitoring app to cover everything.
The app is also not the right choice for someone who wants no notifications or financial prompts at all. Its value comes from staying engaged with credit, so a person who prefers a completely passive experience may find the monitoring concept more distracting than helpful. In that case, a bank’s occasional score display could be enough, even if it offers less context.
How it compares with the usual alternatives
There are three broad alternatives I would consider. The first is a bank or card issuer’s built-in credit view. That option is convenient because it is already near the accounts I use, and it may be sufficient for a quick glance. Credit Sesame is the better fit when I want a more dedicated credit-focused experience rather than a small feature inside everyday banking.
The second alternative is a full budgeting app. Budgeting tools are usually stronger for tracking spending categories, planning bills, and seeing where monthly income goes. Credit Sesame is not a substitute for that kind of household cash-flow system. I would pair the two if my main goal were both spending control and credit awareness.
The third alternative is a specialist service for debt counseling, identity issues, or detailed financial planning. Those services may be more appropriate when the problem is urgent or complicated. Credit Sesame can help me notice that I need assistance, but I would not confuse a monitoring app with personalized professional advice.
This comparison makes the decision fairly simple. Choose Credit Sesame when the missing piece is visibility: you want a recurring view of credit, alerts, and guidance in one dedicated place. Choose a different tool when your central need is transaction budgeting, formal counseling, lender paperwork, or a highly customized plan.
Small changes that make the app more useful
I would begin by setting a consistent review routine instead of opening the app whenever I feel anxious. A monthly check can be enough for many people, while someone actively preparing for a major application may reasonably look more often. The goal is to notice meaningful developments without turning normal score movement into a daily source of stress.
When an alert appears, I would record what I expected to see and what surprised me. This simple comparison can reveal whether the issue is a new account, a balance change, a reporting delay, or something that deserves direct follow-up. It is more reliable than immediately guessing at the cause.
I would also use the app before, not during, major decisions. Before applying for credit, I could review my situation and avoid submitting applications impulsively. Multiple applications, timing, and existing balances can all matter, so a pause for review is often more valuable than chasing a quick score improvement.
Finally, I would keep official records separate. Credit Sesame is a convenient dashboard, but account statements, creditor correspondence, and formal reports remain important when accuracy matters. This is a non-obvious but essential trade-off: convenience improves awareness, while original documents provide the evidence needed to resolve a serious issue.
The cost of switching from another credit tool
Moving to Credit Sesame should be relatively easy if I currently use only a bank’s score display, because the main change is adopting a dedicated monitoring routine. The larger cost is mental rather than technical: I need to learn where the app places its guidance, decide which notifications deserve attention, and stop comparing every small difference with numbers shown elsewhere.
If I already use a budgeting platform, switching completely may be the wrong goal. I would keep the budgeting tool for spending and use Credit Sesame only for credit-related monitoring. Duplicating every financial task across several apps creates clutter, but using each service for its strongest purpose can be efficient.
Someone who has built a detailed workflow around a specialist credit service should switch only if the simpler, focused experience solves a real problem. If the current service provides the exact reports, dispute support, or planning features I need, convenience and familiarity may outweigh the appeal of a free alternative. The right test is whether Credit Sesame improves my decisions, not whether it has more screens.
Who should use it and who should skip it
I would recommend it to a first-time credit user who wants a less intimidating place to begin. It can also suit someone rebuilding financial habits, preparing for a future rental or loan application, or simply tired of checking credit through several unrelated accounts.
It is a good match for people who respond well to reminders and short explanations. The app gives credit a regular place in the financial routine, which can be helpful when the alternative is forgetting about it for months.
I would be more cautious recommending it as the only finance app for someone who needs detailed expense tracking, shared household budgeting, tax organization, or debt counseling. Those needs call for different tools. I would also skip it if notifications about credit would increase anxiety and I had no intention of reviewing them calmly.
My recommendation after using it
Credit Sesame earns my recommendation as a free, approachable credit-monitoring app rather than as an all-purpose financial command center. Its strongest value is helping me build awareness before a credit decision becomes urgent. The combination of score visibility, alerts, and guidance gives beginners a practical starting point and gives experienced users a convenient way to keep watch.
I would install it when I want one dedicated place to follow credit and learn from changes. I would not rely on it alone for disputes, complex debt decisions, or detailed budgeting. Used with that boundary in mind, it avoids the most common mistake people make with credit apps: expecting a number to do the work that consistent financial behavior must do.
For me, the deciding advantage is not the promise of an instant improvement. It is the chance to replace guesswork with a repeatable review habit. If that is what you need, Credit Sesame is a sensible choice. If your real problem is spending control or specialized financial advice, keep looking for a tool built around that job instead.
Pros
- Free credit score updates help you monitor changes over time.
- Personalized recommendations can suggest ways to improve your credit profile.
- Identity theft monitoring may alert you to suspicious activity.
- The interface is simple enough for first-time credit users.
- Useful loan and credit card comparisons are available in one place.
Cons
- Some features and offers vary depending on your location and credit profile.
- Personalized product recommendations may feel like targeted advertising.
- Credit score information may differ from scores used by some lenders.
- You may need to provide sensitive financial and identity information.
- The app can send frequent notifications about offers and account updates.
FAQs for Credit Sesame: Grow your score
What is Credit Sesame: Grow your score used for?
Credit Sesame: Grow your score is designed to help users monitor and understand their credit profile. It typically provides access to credit-score information, factors that may influence the score, personalized recommendations, identity-protection features, and financial product suggestions. After installing the app, users can review their credit information in one place and receive alerts or guidance intended to support healthier credit habits over time.
Is Credit Sesame: Grow your score free to download and use?
The app is generally available to download without an upfront fee, and many of its core credit-monitoring tools can be used at no cost. However, some optional services, financial products, or premium features may have separate terms, eligibility requirements, or costs. Before accepting an offer, read the displayed conditions carefully, since recommendations inside the app may involve third-party providers and are not automatically free.
Will using Credit Sesame affect my credit score?
Checking your own credit information through a personal-finance app generally uses a soft inquiry, which does not normally lower your credit score. Credit Sesame’s monitoring and educational tools are intended to let you review your information without applying for credit. Nevertheless, if you choose to apply for a loan, card, or another product advertised through the app, the provider may perform a hard inquiry that could affect your score.
What personal information does Credit Sesame require?
Because Credit Sesame provides personalized credit information and financial recommendations, it may request identifying details such as your name, address, date of birth, and Social Security number, along with account credentials or verification information. These details are used to match your identity and retrieve relevant data. Before creating an account, review the app’s privacy policy, permissions, security practices, and data-sharing explanations.
Is Credit Sesame accurate, and can it improve my credit score directly?
Credit Sesame can be useful for tracking changes, identifying possible issues, and learning which behaviors may influence your credit profile, but it does not directly repair or raise your score by itself. Information may come from a particular credit bureau or use a scoring model that differs from the one a lender checks. Treat the app as an educational monitoring tool, verify important discrepancies with the relevant bureau, and make payments on time.

Credit Sesame: Grow your score
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via help@creditsesame.com, visit http://help.creditsesame.com, or review their http://www.creditsesame.com/about/privacy-policy/.










